Charitable Donations Without Receipts: The Rules
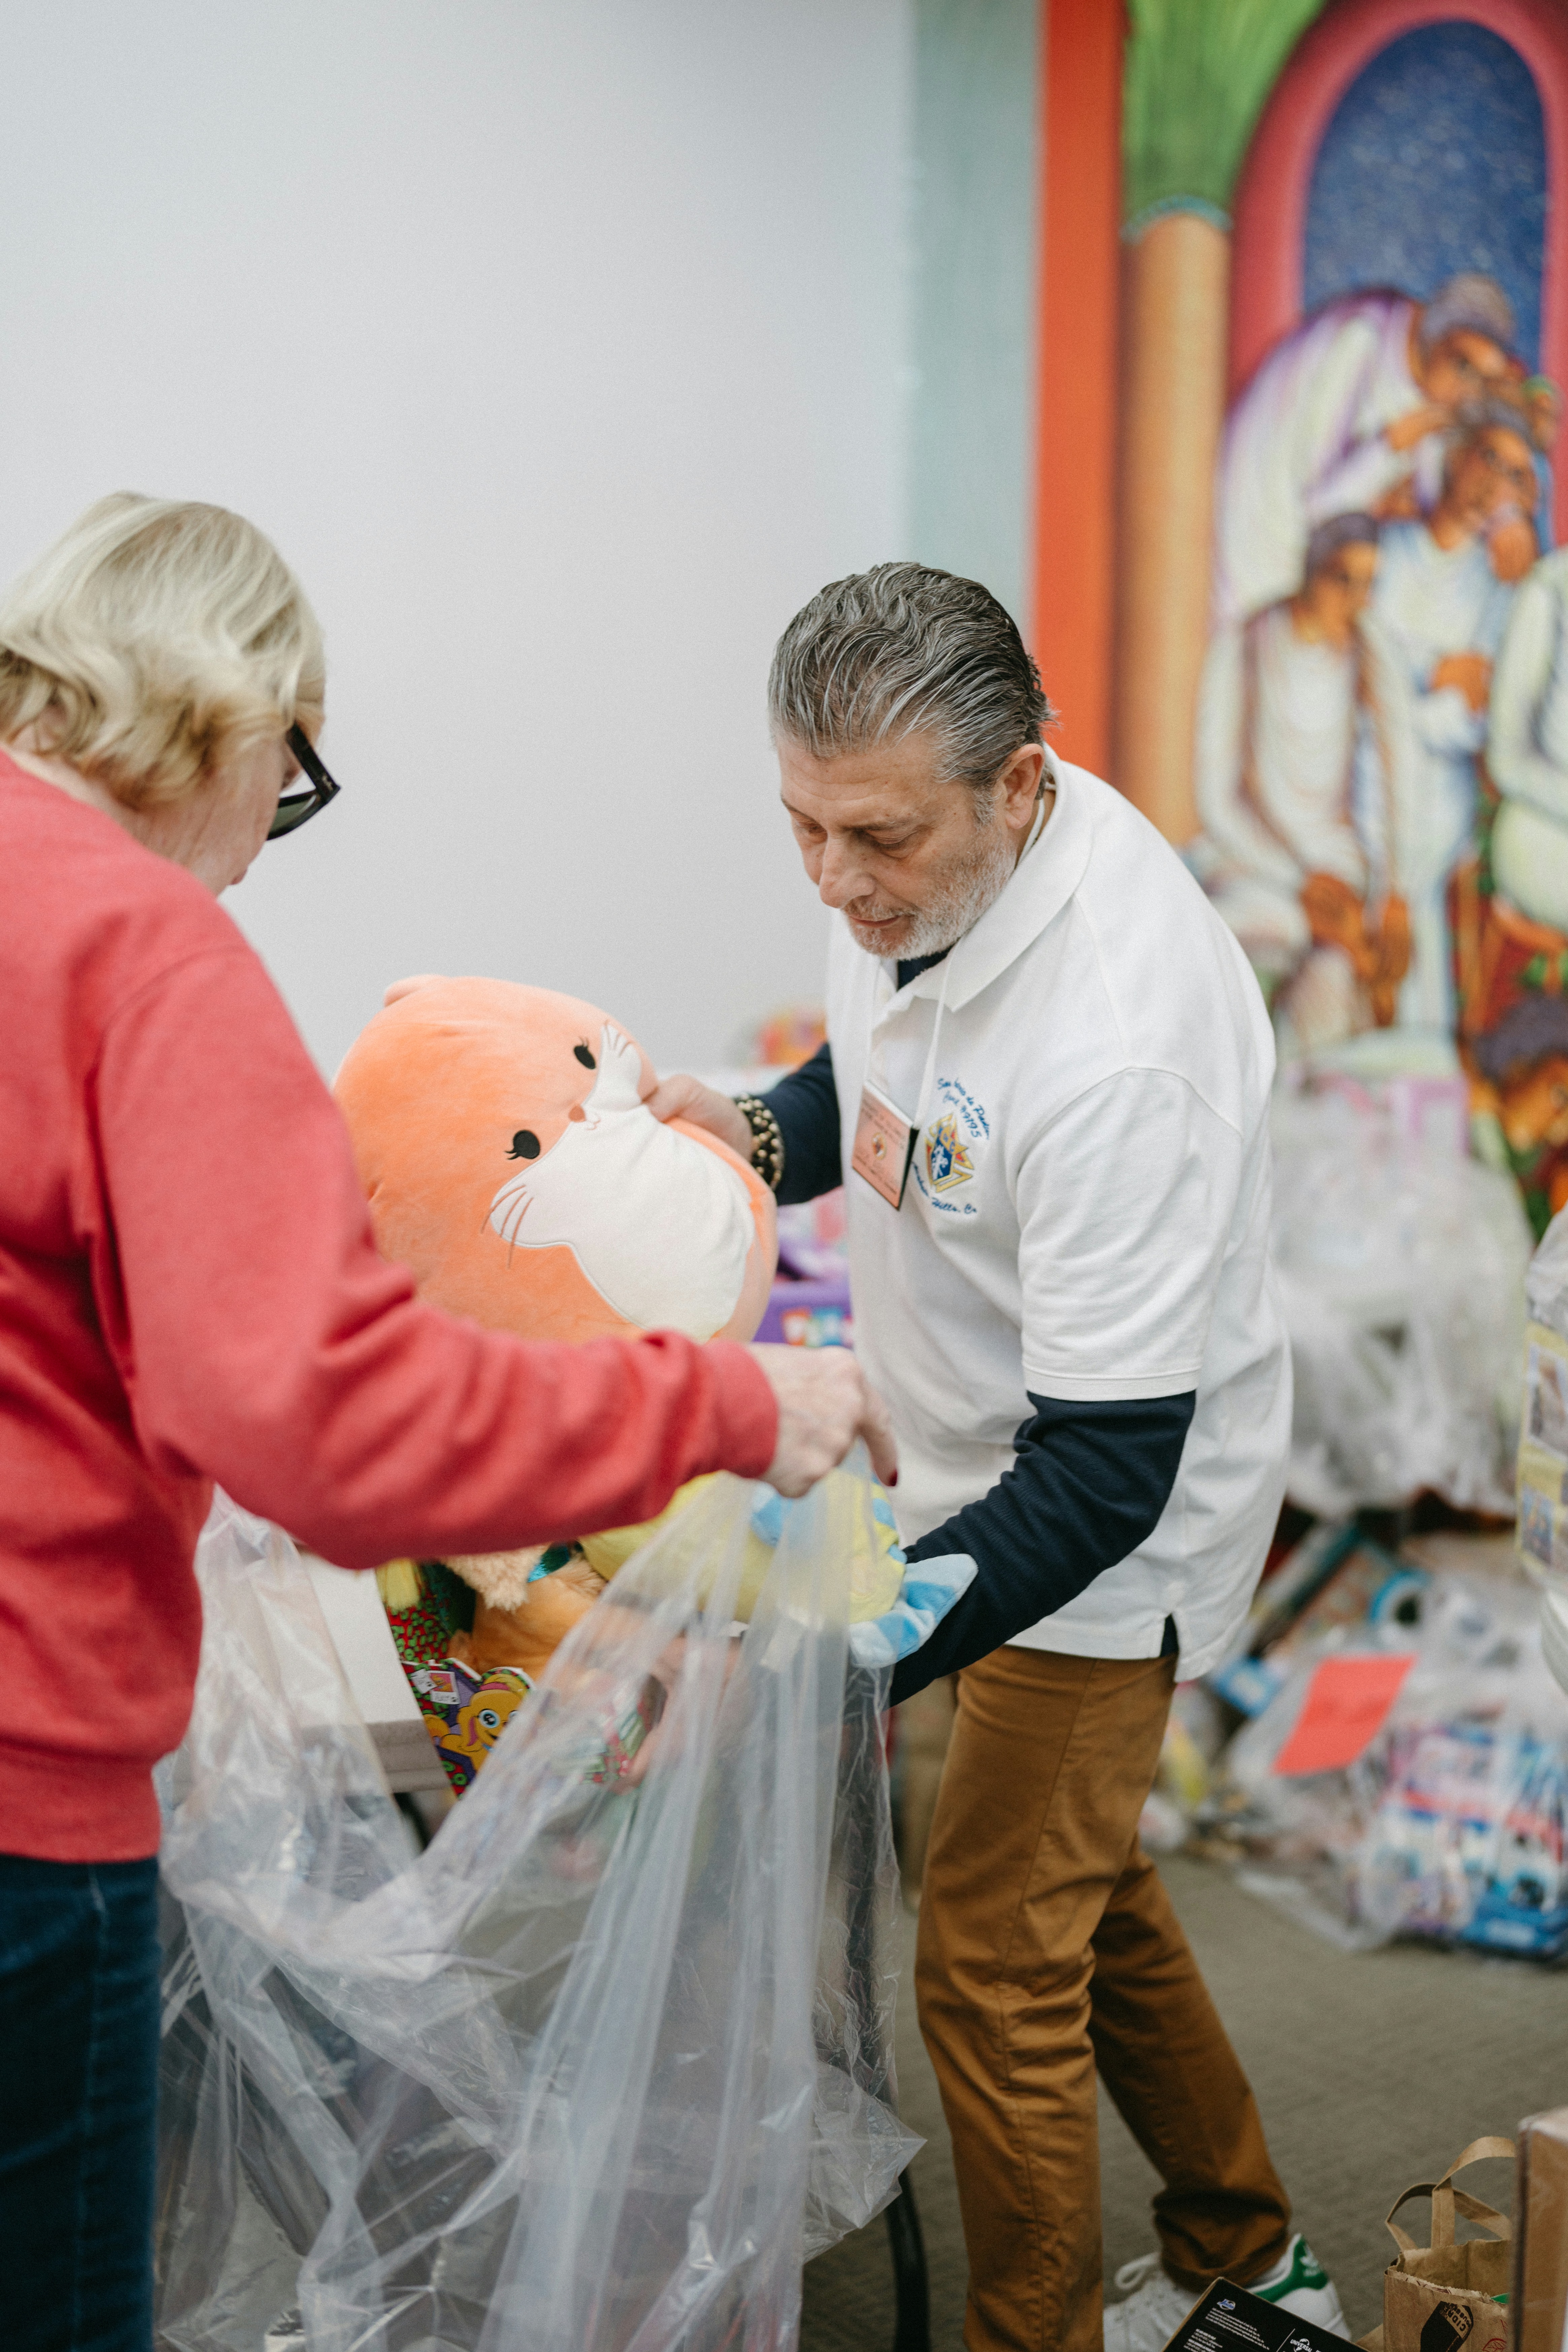
You spent a Saturday clearing out your parents' garage and drove three carloads of furniture, clothing and old kitchen equipment to the St. Vincent de Paul donation center. Nobody handed you a detailed receipt, just a stack of blank forms and a rushed volunteer who was juggling four other drop-offs at once. Now it is tax season, you have no idea what any of it was worth, and you are wondering whether you can claim any of it at all.
Most people assume the answer is simple: no receipt, nothing counts. That is not quite right, and the actual rule is more forgiving than most Catholics realize, as long as you understand where the thresholds sit and what the IRS expects at each one.
The Rule Is Graduated, Not All or Nothing
There is no single dollar amount above which you suddenly need paperwork and below which none of it matters. Instead, the documentation the IRS expects scales with the size of the gift. A five dollar bill in the collection basket and a $50,000 gift of appreciated stock are both governed by the same charitable contribution rules, but they sit at very different points on the same ladder.
Understanding where your gift falls on that ladder protects the deduction you already earned by giving, and it protects you if the IRS ever asks a question about your return.
What are the Thresholds?
For any single cash gift under $250, a bank record, such as a canceled check or a bank or credit card statement, or a written communication from the charity showing its name, the date and the amount is enough. You do not need a formal receipt for every five or ten dollar gift in the basket, as long as the payment method itself leaves a trail.
For any single cash gift of $250 or more, the rules tighten. The IRS requires a contemporaneous written acknowledgment from the organization, meaning a letter or statement received before you file your return, confirming the amount and stating whether you received anything of value in exchange. IRS Topic 506 covers this threshold directly.
Non-cash gifts follow a separate scale. For total non-cash donations over $500 in a year, such as those boxes from the garage, you must file Form 8283 with your return, describing what you gave and to whom. Above $5,000 for a single item or a group of similar items, Section B of that form requires a qualified appraisal, with one notable exception: publicly traded securities, like shares of stock, do not require an appraisal at any dollar amount because their value is set by the market each day. Above $500,000, the appraisal itself must be attached to your return rather than simply kept on file.
"I Already Gave the Stuff Away. Isn't It Too Late?"
Not necessarily, but it depends on how soon you act. If you dropped off donations within the last few months, most organizations, including St. Vincent de Paul and most parish thrift operations, can still issue a written acknowledgment on request, and it is worth calling before you assume the paperwork is unrecoverable. What you cannot do is manufacture a valuation after the fact for something you no longer have in hand. If the boxes were worth more than $500 combined, a reasonable, good-faith estimate at the time of the gift, kept in your own records, is far more defensible than a number you reconstruct in April. Where the total is significant, your accountant can advise on how to substantiate the value; this is exactly the kind of detail we encourage families to bring to their CPA or attorney rather than resolve alone.
Good Records Are What Let Your Generosity Count
None of this paperwork changes what you actually did. You still cleared out the garage, and the furniture and clothing still went to families who needed them. Documentation is not a test of your generosity. It is simply what allows the deduction to catch up to a gift you already made. Families who keep a simple running log of what they gave and to whom, updated a few times a year rather than reconstructed once in April, tend to find that giving larger, more meaningful gifts, including a gift of stock or property to support a parish or a fund at The Orange Catholic Foundation, feels far less intimidating once they trust their own records.
A habit worth building now, before you are standing in a garage full of boxes: take a few photos of larger household donations before you drop them off and jot down a rough item count and condition on your phone. It takes two minutes, and it gives you something concrete to work from if a charity's own paperwork is thin or delayed. None of this replaces the written acknowledgment the organization owes you. It just means you are not starting from memory alone if that acknowledgment is slow to arrive.
Ask a Sibling to Keep the Log With You
If you share responsibility for a parent's estate or a family cleanout with a sibling, agree now on who tracks what gets donated and where. A shared, simple log prevents two people from guessing separately in April, and it makes any future gift involving the same property or estate far easier to document correctly. This is a small conversation to have early, and most families are glad they had it once tax season actually arrives.
Your Next Step
If you are considering a larger non-cash gift this year, whether it is appreciated stock, a piece of property or a significant personal collection, the documentation requirements are more specific than for a bag of clothing. Getting it right from the start matters. Schedule a meeting with The Orange Catholic Foundation before you make the gift, or browse the full range of ways to give to see which approach fits what you are hoping to donate.
Frequently Asked Questions
Do I need a receipt for every donation, no matter how small?
No. For any single cash gift under $250, a bank record or a simple written note from the charity showing the amount and date is enough. The written acknowledgment requirement only applies once a single gift reaches $250 or more.
What happens if I give more than $500 worth of household items or other property in a year?
Once your total non-cash donations for the year exceed $500, you must file Form 8283 with your tax return describing the items and where they were donated. Above $5,000 for a single item or a group of similar items, a qualified appraisal is also required, except for publicly traded securities.
Do I need an appraisal to donate stock to my parish or a fund at the Foundation?
No. Publicly traded securities are valued using market data on the date of the gift, so no qualified appraisal is required regardless of the dollar amount. This is one of the few exceptions to the general non-cash appraisal rule, and it is part of why a stock gift is often simpler to document than a gift of real estate or personal property.
What if I can't find my giving records from earlier in the year?
Start with your bank and credit card statements, which cover most cash gifts under $250 on their own. For larger gifts, contact the organization directly and ask for a written acknowledgment or a copy of any receipt they issued at the time. Acting promptly gives the organization the best chance of locating its own records.
This information is intended to be general in nature and is not offering professional tax, legal or accounting advice. Please discuss your philanthropic giving with your accountant or other professional advisors. The Orange Catholic Foundation is a 501(c)(3) charitable corporation, Tax ID 33-0934571.